Loading market data...
Fri, 25 Sept 2026
11:40:13 pm
Fri, 25 Sept 2026
11:40:13 pm
Rudransh Sangwan
Published at: September 25, 2026, 11:55 AM
Synopsis
SPR Auto Technologies shares rose nearly 49% in six months. Motilal Oswal retained a Buy rating with a Rs 6,150 target, citing growth and margins.
Shares of SPR Auto Technologies Limited rose 1.55% to Rs 4,589.6 on BSE during Friday's trading session on September 25. The stock had touched an intraday high of Rs 4,633, while its market capitalisation stood at Rs 21,289.44 crore at 12:53 PM.
Motilal Oswal Financial Services has retained a "Buy" rating on SPR Auto Technologies with a target price of Rs 6,150 per share. Based on the brokerage's cited current market price of Rs 4,494, the target implies about 37% upside.
The brokerage expects SPR Auto Technologies to benefit from margin expansion at its subsidiaries, a stable standalone business and an improving balance sheet. It also expects the company to move further toward a diversified mobility platform through acquisitions and expansion across different powertrain technologies.
Loading chart...
SPR Auto Technologies has delivered strong gains across several periods in 2026. The detailed performance figures provided show a 14.42% rise over three months, a 49.23% gain over six months and a 46.51% increase so far in 2026. The material also cites a six month gain of 47% in its summary, creating a small difference between the headline figure and the detailed return data.
| Period | Share price performance |
|---|---|
| Three months | 14.42% |
| Six months | 49.23% |
| One year | About 76% |
| 2026 so far | 46.51% |
| September 25 intraday move | 1.55% higher |
The stock's recent movement comes as the company works to expand beyond its traditional piston manufacturing business. SPR Auto Technologies is seeking growth through acquisitions and businesses that can serve multiple powertrain technologies.
Motilal Oswal has initiated coverage on SPR Auto Technologies with a "Buy" rating and a target price of Rs 6,150. The brokerage said the stock was trading at 23.7 times estimated FY28 earnings per share and 20.4 times estimated FY29 earnings per share at a cited market price of Rs 4,494.
The Rs 6,150 target is based on a valuation of 30 times estimated September 2028 earnings per share, according to the brokerage. This valuation approach is one of the main reasons behind the target price.
| Particulars | Details |
|---|---|
| Motilal Oswal rating | Buy |
| Target price | Rs 6,150 |
| Cited current market price | Rs 4,494 |
| Implied upside | 37% |
| FY28 estimated EPS multiple | 23.7 times |
| FY29 estimated EPS multiple | 20.4 times |
| Target valuation | 30 times September 2028 estimated EPS |
The rating and target are the brokerage's views. They are not a guarantee of future share price performance.
Motilal Oswal expects SPR Auto Technologies to post a 21% compound annual growth rate in profit after tax. The brokerage's view is based on a stable standalone business and faster growth from the company's subsidiaries.
Margin expansion is another part of the earnings outlook. The brokerage expects stronger margins at subsidiaries to support profitability while limited growth in capital spending could help the balance sheet.
SPR Auto Technologies is also targeting opportunities across CNG, ethanol, hydrogen and hybrid powertrains. Motilal Oswal said the company is benefiting from rising demand across these areas, along with aftermarket demand.
The brokerage also pointed to the exit of some global competitors from the internal combustion engine ecosystem as a factor supporting SPR Auto Technologies' opportunity in the market.
SPR Auto Technologies is using acquisitions to diversify its business. The company has been reinvesting in businesses including Antolin, Takahata, TGPEL and EMFi.
The strategy is aimed at moving SPR Auto Technologies beyond a traditional piston manufacturing model. The company is instead building exposure to a wider range of mobility and powertrain related businesses.
The development follows a broader pattern seen across the auto components industry, where companies are expanding into new vehicle technologies while continuing to serve existing internal combustion engine demand. WeloMoney has also covered developments involving the auto ancillary sector, including companies expanding their position in electric vehicle components.
SPR Auto Technologies recently completed a Rs 10 billion qualified institutional placement. Motilal Oswal expects the funds to support future organic and inorganic growth opportunities.
The QIP gives the company additional funding capacity for acquisitions and business expansion. The brokerage considers this an important factor in its valuation view because future investments could help the subsidiaries scale.
| Growth factor | What the brokerage expects |
|---|---|
| QIP | Rs 10 billion raised for future growth |
| Subsidiaries | Faster scale up |
| Margins | Further expansion |
| Capital spending | Limited growth |
| Balance sheet | Improvement |
| Acquisitions | More diversification |
The use of QIP proceeds and the pace at which new businesses contribute to earnings will therefore remain important areas to track.
The company is headquartered in Delhi and has traditionally been associated with piston manufacturing. Its current strategy is broader, with acquisitions and investments aimed at creating a powertrain agnostic mobility business.
The shift gives SPR Auto Technologies exposure to several parts of the vehicle technology market. At the same time, the company continues to operate its standalone business, which Motilal Oswal expects to remain stable.
The company's approach can also be viewed alongside other auto component companies expanding into new vehicle technologies. For example, Lumax Auto Technologies shares have also drawn market attention following a strong share price move.
The brokerage's outlook places several operating factors in focus over the coming quarters:
Investors will also be able to track whether the expected 21% profit after tax compound annual growth rate develops as projected. Changes in margins, capital spending and the contribution from subsidiaries will provide further information on the company's earnings path.
The share price was at Rs 4,589.6 during the cited trading session, while the brokerage's target stands at Rs 6,150. The gap between those two prices reflects the brokerage's valuation view and does not establish where the stock will trade in the future.
Motilal Oswal has set a target price of Rs 6,150 for SPR Auto Technologies and retained a "Buy" rating. The brokerage's cited market price was Rs 4,494, implying about 37% upside to its target.
SPR Auto Technologies shares have risen 49.23% over six months based on the detailed performance figure provided. The supplied material also cites a 47% six month gain in its summary.
Motilal Oswal expects SPR Auto Technologies to benefit from stable standalone operations, faster growth at subsidiaries and margin expansion. The brokerage estimates a 21% compound annual growth rate in profit after tax.
SPR Auto Technologies completed a Rs 10 billion qualified institutional placement. The funds are expected to support future organic and inorganic growth opportunities.
SPR Auto Technologies is diversifying through acquisitions involving businesses such as Antolin, Takahata, TGPEL and EMFi. The company is also targeting opportunities linked to CNG, ethanol, hydrogen and hybrid powertrains.
SPR Auto Technologies was trading at Rs 4,589.6 on BSE at 12:53 PM on September 25, with the stock up 1.55% during the session. It had touched an intraday high of Rs 4,633.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
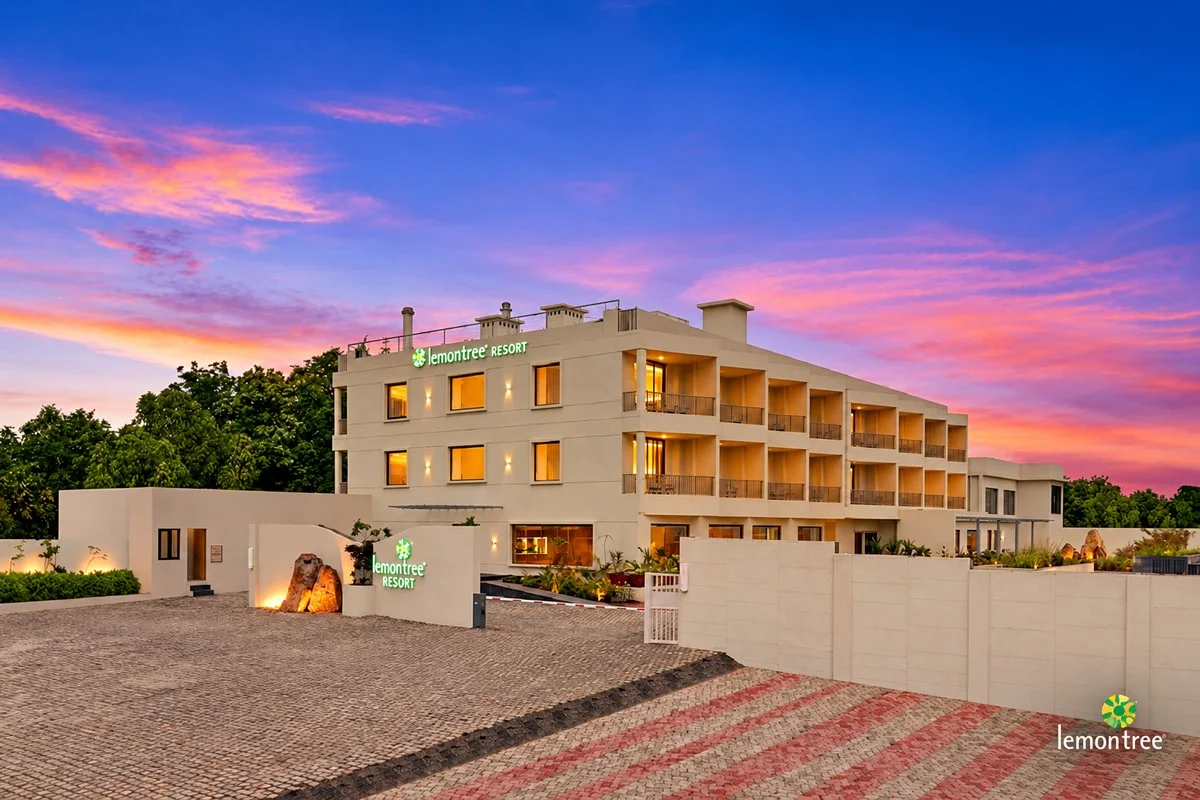
Lemon Tree Hotels will develop a 172 room Bandra hotel after buying land for Rs 120 crore, while a new 90 room Patancheru hotel expands its Telangana...
Dixon Technologies is expanding into IT hardware, data centres and defence as it targets the global top five.
Sterlite Technologies has launched Neuralis fibre cables with up to 6,912 fibres, factory fitted connectors and options for large data centres.
Cubex Tubings shares gain 74% in four sessions after a Rs 135 crore fundraising plan. The EGM is scheduled for October 28, 2026.
Texmaco Rail shares gained 60% in FY27. Ventura Securities sees 32% upside to Rs 165 after a technical breakout, with Rs 102 stop loss.