Loading market data...
Wed, 21 Oct 2026
05:02:56 pm
Wed, 21 Oct 2026
05:02:56 pm
Rudransh Sangwan
Published at: July 23, 2026, 6:31 AM
Synopsis
IndusInd Bank shares dropped 5% despite reporting strong Q1 FY27 earnings. Net profit rose 46.5%, NII beat estimates, but brokerages remained cautious over weak NIM, fee income, and the pace of recovery.
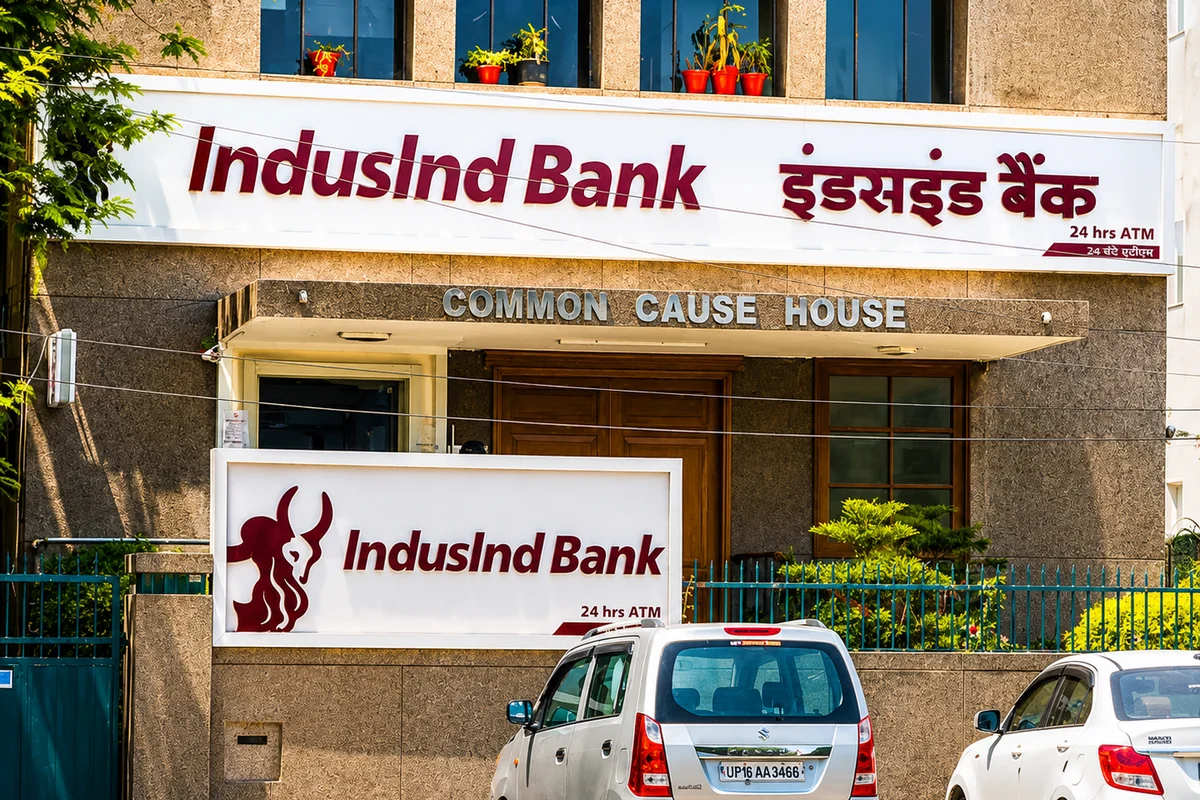
IndusInd Bank Ltd shares declined nearly 5% on July 23, emerging among the top losers on both the BSE 500 and NSE 500, despite reporting a stronger-than-expected set of Q1 FY27 earnings. The decline followed cautious brokerage commentary, with analysts noting that the earnings beat was primarily driven by lower operating expenses and reduced credit costs, while the bank's core operating metrics remained under pressure.
Although the private lender delivered better-than-expected profit, improved asset quality, and higher net interest income, concerns over net interest margin (NIM), fee income growth, and the sustainability of the recovery kept investor sentiment subdued.
Loading chart...
IndusInd Bank shares witnessed selling pressure despite the positive earnings announcement.
| Stock Performance | Value |
|---|---|
| Share Price Decline | Around 5% |
| Intraday Price | ₹1,015.75 |
| Market Capitalisation | ₹79,250 crore |
| 2026 Stock Performance | +14.3% |
| Nifty 50 Performance (2026) | -8.3% |
Despite Thursday's decline, the stock has significantly outperformed the benchmark index so far in 2026.
The lender reported a solid earnings performance that exceeded market expectations.
| Metric | Q1 FY27 | YoY Change |
|---|---|---|
| Net Profit | ₹1,002.5 crore | +46.5% |
| Net Interest Income (NII) | ₹4,685 crore | +1% |
| Net Interest Margin (NIM) | 3.57% | Up from 3.46% |
| Gross NPA | 3.25% | Improved from 3.43% (QoQ) |
| Net NPA | 0.95% | Improved from 1.00% (QoQ) |
| Provisions | Lower YoY | Positive |
Both net profit and NII exceeded analyst estimates, while asset quality continued to improve sequentially.
IndusInd Bank delivered another quarter of improving asset quality.
The Gross Non-Performing Asset (GNPA) ratio declined to 3.25% from 3.43% in the previous quarter, while the Net NPA ratio improved to 0.95% from 1.00%. Lower provisioning requirements also supported profitability during the quarter.
However, brokerages noted that much of the earnings improvement came from lower credit costs rather than stronger operating performance.
Despite the earnings beat, brokerage opinions remained mixed as concerns over core profitability persisted.
| Brokerage | Rating | Target Price | Key View |
|---|---|---|---|
| JPMorgan | Underweight | ₹820 | Earnings supported by lower provisions; weak core trends remain |
| CLSA | Underperform | ₹925 | Weak fee income, soft NIM, corporate-led loan growth |
| Jefferies | Buy | ₹1,250 | Improving asset quality, profitability and loan growth support recovery |
JPMorgan retained its Underweight rating while raising its target price to ₹820.
According to the brokerage:
CLSA downgraded the stock to Underperform and increased its target price to ₹925.
The brokerage highlighted:
Jefferies maintained its Buy rating and increased its target price to ₹1,250.
The brokerage believes:
IndusInd Bank reported a strong Q1 FY27 earnings performance, comfortably beating market expectations on profit and net interest income while continuing to improve asset quality. However, investors remained cautious as brokerages highlighted persistent pressure on core operating metrics such as net interest margin, fee income, and sustainable profitability.
Going forward, the bank's ability to improve operating performance, expand margins, strengthen fee income, and deliver higher returns on assets will be key factors influencing stock performance.
The stock declined after brokerages said the earnings beat was largely driven by lower provisions and operating costs rather than stronger core banking performance.
Net profit increased 46.5% year-on-year to ₹1,002.5 crore.
Net Interest Income (NII) rose 1% to ₹4,685 crore, exceeding analyst expectations.
Jefferies maintained a Buy rating with a target price of ₹1,250.
Brokerages remain concerned about weak fee income, pressure on net interest margins, corporate-led loan growth, and the pace of the bank's long-term recovery.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
eMudhra share price fell 20% to Rs 432 after concerns over weak TLS certificate keys. See the browser trust actions and company's response.
CONCOR volumes rose 0.53% to 14.48 lakh TEUs in the September 2026 quarter. See EXIM and domestic volume trends and year to date growth.
eMudhra shares plunged 20% to Rs 432 after eight intermediate certificate keys were compromised.
L&T won two government building orders worth Rs 2,500 crore to Rs 5,000 crore in Delhi and Amaravati. Both projects involve major office complexes.
Venus Pipes & Tubes begins operations at its spooling facility two months early and secures a ₹185 crore data centre LOI.