Loading market data...
Tue, 29 Sept 2026
11:30:01 am
Tue, 29 Sept 2026
11:30:01 am
Rudransh Sangwan
Published at: September 29, 2026, 9:39 AM
Synopsis
Goldman Sachs retains its Buy rating on IndiGo with a Rs 5,900 target, citing international growth, cost leadership and better FY28 profitability.
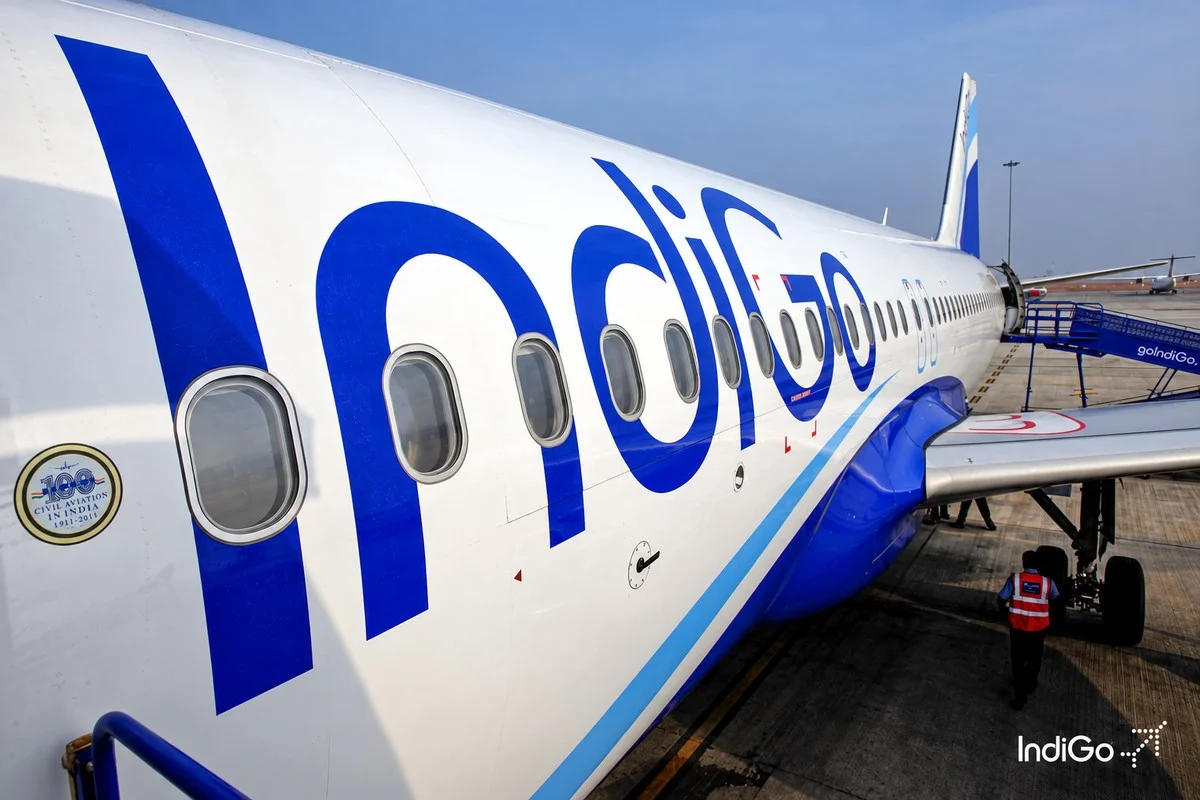
Shares of InterGlobe Aviation, the parent company of IndiGo, were trading higher on Tuesday, September 29, after Goldman Sachs retained its "Buy" rating on the airline and set a target price of Rs 5,900. The target is about 21% above InterGlobe Aviation's Monday closing price of Rs 4,874.50.
Goldman Sachs said it remains positive on IndiGo's growth outlook. The brokerage pointed to the airline's market share gains, industry capacity conditions, cost position and scope for further international growth.
InterGlobe Aviation shares were trading at Rs 4,883.50, up 0.2%, at 12:20 pm on Tuesday. The stock had fallen about 5% in 2026 and was down about 15% over the previous 12 months.
Loading chart...
Goldman Sachs expects moderate additions to the airline industry's fleet over the medium term. The brokerage said this could support yields, while IndiGo's cost position could help improve profitability.
The brokerage also sees significant room for growth in IndiGo's international business. It said the international operation has a long runway for expansion, giving the airline another source of growth beyond its domestic network.
Higher fuel costs remain a near term concern for the airline. Goldman Sachs expects profitability to improve significantly in FY28 despite this pressure. The brokerage values IndiGo at 10.4 times FY28 estimated EV/EBITDAR, using the airline's long term median multiple.
The combination of capacity growth, cost control and international expansion forms the main part of the brokerage's view on IndiGo. Its assessment also places attention on how fuel costs affect profitability as the airline expands.
The gap between the current market price and Goldman Sachs' target remains notable. The target of Rs 5,900 is based on the brokerage's valuation of IndiGo and represents about 21% upside from the previous closing price.
| Particulars | Details |
|---|---|
| Company | InterGlobe Aviation |
| IndiGo share price at 12:20 pm | Rs 4,883.50 |
| Tuesday movement | 0.2% higher |
| Monday closing price | Rs 4,874.50 |
| Goldman Sachs target price | Rs 5,900 |
| Implied upside from Monday close | About 21% |
| FY28 valuation | 10.4 times EV/EBITDAR |
| 2026 stock performance | About 5% lower |
| 12 month stock performance | About 15% lower |
The Tuesday move came despite the stock remaining below its Monday close on an intraday basis earlier in the session. The supplied data shows that InterGlobe Aviation has faced a weaker share price trend during 2026 and over the previous 12 months.
IndiGo's international business is one of the areas Goldman Sachs expects to contribute to longer term growth. The brokerage said there is significant room for expansion in international operations.
That view is also relevant to the airline's broader network plans. IndiGo had added 330 pilots in FY26 as it expanded its network across India and overseas, as covered in an earlier IndiGo network expansion update. The latest brokerage view continues to place international growth among the factors that could shape the airline's future performance.
Fleet additions across the industry are another factor. Goldman Sachs expects these additions to remain moderate over the medium term and said that could support yields. For IndiGo, the effect of capacity growth will need to be considered alongside fuel costs and the airline's ability to maintain its cost position.
Fuel costs remain a pressure point in the Goldman Sachs assessment. Aviation fuel is a major operating cost for airlines, so changes in fuel prices can affect margins and profitability.
The source does not provide a specific fuel price forecast or quantify the expected impact on IndiGo's earnings. Goldman Sachs instead expects a significant improvement in profitability in FY28 while acknowledging higher fuel costs as a near term headwind.
This makes future earnings and profitability an important area to track. The brokerage's FY28 valuation also means that its target price is based on expectations for future financial performance rather than only the airline's current share price.
IndiGo's recent share performance has also been weaker than the target price alone suggests. The stock was down about 5% in 2026 and 15% over the previous 12 months, according to the supplied market data.
The supplied source also cites analyst data showing a broad positive distribution of ratings. Out of 26 analysts, 21 had a "Buy" rating, three had a "Hold" rating and two had a "Sell" rating. The 12 month consensus target price was Rs 5,585.31, which implied nearly 15% upside from the Monday closing price of Rs 4,874.50.
This consensus figure is below the Rs 5,900 target from Goldman Sachs. The difference shows that individual brokerage targets can vary even when the broader analyst view points in the same direction.
For readers tracking the stock, the rating distribution and target prices provide one part of the market picture. Actual share price performance will also depend on earnings, operating costs and developments in the airline industry.
The latest Goldman Sachs view puts several factors on the watch list for InterGlobe Aviation.
The airline's cost position is another factor highlighted by Goldman Sachs. The brokerage expects this position to support profitability as the business grows.
Investors can also track future brokerage estimates and the gap between market prices and published target prices. A target price is an analyst estimate and does not guarantee a future market price.
InterGlobe Aviation has remained under pressure over the broader period covered by the supplied data, with the stock down about 5% during 2026 and 15% over the previous 12 months. The Tuesday session showed only a modest 0.2% gain at 12:20 pm.
The airline's share performance also needs to be viewed alongside operating factors. Fuel costs can affect profitability, while fleet additions and international expansion can influence capacity and future revenue opportunities.
An earlier IndiGo share price update focused on the impact of earnings and crude oil prices. The latest Goldman Sachs assessment puts more attention on future profitability, international growth and industry capacity.
InterGlobe Aviation is the parent company of IndiGo, the airline discussed in the Goldman Sachs assessment. The supplied source focuses on IndiGo's market share, cost position, fleet conditions and international business as the main factors behind the brokerage's outlook.
The latest development is therefore centered on the brokerage's updated assessment of the airline's future earnings and growth prospects, rather than a new corporate action by InterGlobe Aviation.
Goldman Sachs has a target price of Rs 5,900 for IndiGo's parent InterGlobe Aviation. The target is about 21% above the Monday closing price of Rs 4,874.50.
Goldman Sachs has retained its "Buy" rating on InterGlobe Aviation. The brokerage said its view is supported by market share gains, industry capacity conditions, cost position and international growth potential.
InterGlobe Aviation shares were trading at Rs 4,883.50, up 0.2%, at 12:20 pm on September 29, 2026. The previous session's closing price was Rs 4,874.50.
Goldman Sachs cited IndiGo's market share gains, favourable industry capacity conditions, cost position and long term international growth potential. The brokerage also expects moderate fleet additions to support yields and expects profitability to improve in FY28.
The 12 month consensus target price cited in the source is Rs 5,585.31, compared with Goldman Sachs' target of Rs 5,900. The cited analyst data showed 21 Buy ratings, three Hold ratings and two Sell ratings among 26 analysts.
Fuel costs, industry fleet additions, yields, international growth and IndiGo's cost position could affect profitability. Goldman Sachs expects significant improvement in profitability in FY28 while treating higher fuel costs as a near term headwind.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
NSE shares fell after listing at Rs 1,800, dropping to 12th by market value. Experts identify Rs 1,760 support and Rs 1,795 resistance.
Kirloskar Oil Engines posted 16% Q1 FY27 revenue growth, while margins missed estimates. Motilal Oswal cut earnings estimates and raised its target...
Landmark Cars shares rose 12% to Rs 535.80 after adding BYD and M&M outlets, taking its network to 143 locations, with EV sales at 30% of Q1FY27 new...
Tata Motors’ subsidiary acquired 26,000 shares in Mateshwari E-Smart Mobility for ₹2.6 lakh.
Jio Financial Services shares slide about 26% in 2026 and hit a 52-week low. See key support at ₹205–₹200, resistance near ₹230 and reversal signals...