Loading market data...
Tue, 06 Oct 2026
03:01:40 pm
Tue, 06 Oct 2026
03:01:40 pm
Rudransh Sangwan
Published at: October 6, 2026, 1:40 PM
Synopsis
Monarch expects Krishna GVK's earnings to grow with Taj Santacruz consolidation and Taj Yelahanka, while the stock remains 26% below its yearly peak.
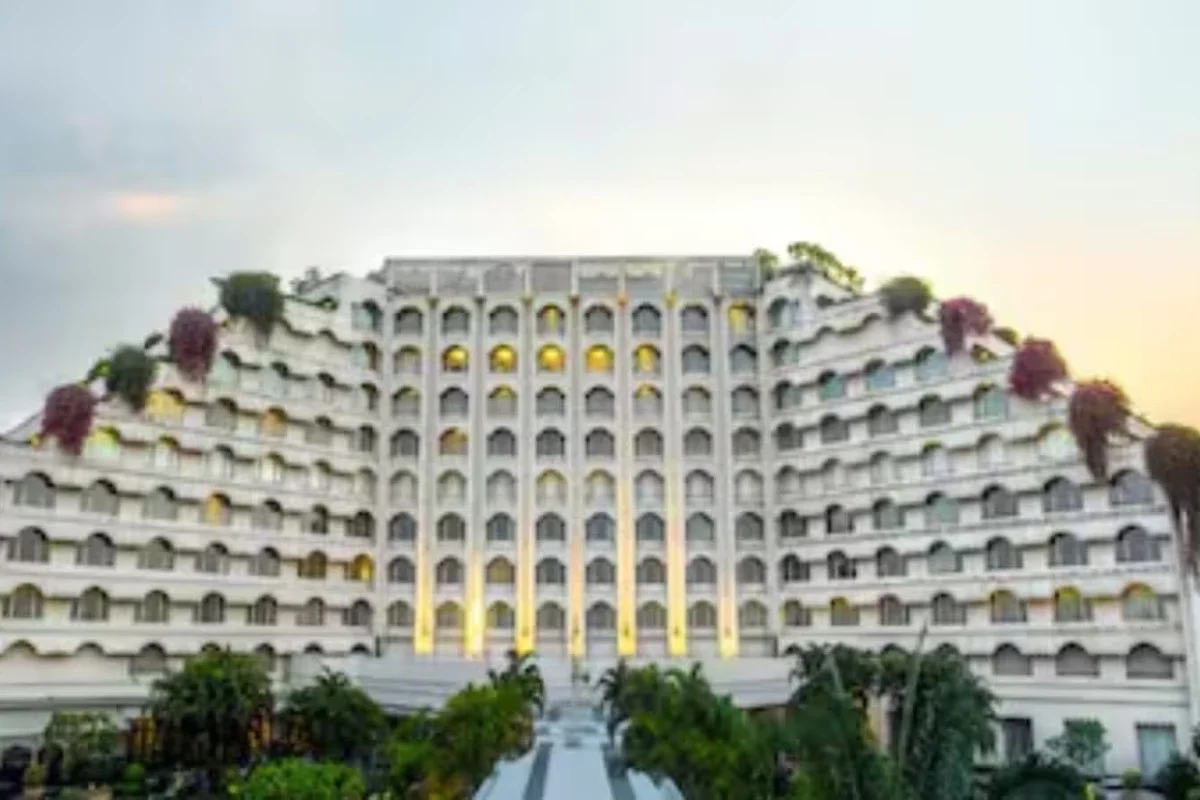
Krishna GVK, formerly known as Taj GVK Hotels & Resorts, has received a BUY rating from Monarch Network Capital Research, which has set a target price of Rs 475. The target implies an upside of about 49% from the stock's last traded price of Rs 319.
The brokerage expects the hotel company to enter a new growth phase, supported by higher room rates at its existing properties, consolidation of Taj Santacruz in Mumbai and the planned Taj Yelahanka hotel in Bengaluru.
The stock has remained weak over the past year despite its longer term gains. It rose more than 1.5% in the latest session to an intraday high of Rs 320 on the BSE, but remained about 27% below its 52 week high of Rs 438.85.
Monarch Network Capital Research has started coverage on Krishna GVK with a BUY rating and a Rs 475 target price. The brokerage has valued the company at 8 times FY29 estimated EV/EBITDA.
The brokerage said Krishna GVK has a combination of owned luxury hotel assets and access to the Taj operating platform. It also pointed to the company's low leverage and expected earnings growth as reasons for assigning the valuation multiple.
Monarch expects the company's earnings profile to change from FY27 as Taj Santacruz becomes fully consolidated and the 256 key Taj Yelahanka property in Bengaluru starts operations.
The brokerage expects Krishna GVK's revenue to grow at a 26.4% CAGR between FY26 and FY29, while earnings per share are estimated to grow at a 15.4% CAGR over the same period.
The stock has faced pressure across several time periods. It has fallen more than 4% over the past month and around 7% over three months. The six month decline is about 1%, while the stock has lost nearly 26% over the past year.
The longer term record is stronger. Krishna GVK shares have gained around 126% over five years.
| Share price measure | Figure |
|---|---|
| Latest traded price used by Monarch | Rs 319 |
| Intraday high in latest trade | Rs 320 |
| 52 week high | Rs 438.85 |
| 52 week low | Rs 281.85 |
| One month performance | Down more than 4% |
| Three month performance | Down around 7% |
| Six month performance | Down around 1% |
| One year performance | Down nearly 26% |
| Five year performance | Up around 126% |
| Monarch target price | Rs 475 |
| Implied upside | Around 49% |
The stock touched its 52 week high of Rs 438.85 in December last year and its 52 week low of Rs 281.85 in March 2026.
The recent share price movement can be viewed alongside other Indian stock market developments covered in recent stock market updates.
Krishna GVK has a strong presence in Hyderabad, where it operates Taj Krishna, Taj Deccan and Vivanta Hyderabad. Together, these three properties have 597 rooms and account for about 42% of Hyderabad's luxury hotel inventory, according to Monarch.
Occupancy at the three hotels stood at 78%, 81% and 83%, respectively. The brokerage therefore sees limited room for a large increase in occupancy from current levels.
Instead, Monarch expects higher average room rates, refurbishment and premiumisation to support revenue per available room and earnings.
The brokerage estimates average room rates to grow at a 12.7% CAGR between FY26 and FY29. It expects demand for premium hotels in Hyderabad to be supported by the city's GCC, IT, pharmaceutical and MICE activity, along with improving airport traffic.
This makes room rate growth an important part of the brokerage's earnings outlook, as further occupancy gains may be more limited across the existing Hyderabad portfolio.
Taj Santacruz in Mumbai is another major part of the growth outlook. Krishna GVK has increased its stake in the property to 51%.
Following the increase, Taj Santacruz is expected to be fully consolidated from Q1FY27. Monarch expects the consolidation to lift the company's reported revenue and EBITDA.
The change is important because it adds a larger owned asset to the company's reported financial base. The brokerage expects the impact from Taj Santacruz to be visible before the Bengaluru expansion reaches full operating scale.
The company is therefore moving into a period where existing hotels, higher room rates and additional consolidated capacity can contribute to earnings at the same time.
Krishna GVK is also developing Taj Yelahanka, a 256 key luxury hotel in North Bengaluru. Monarch expects the property to start operations in H2FY27.
The brokerage sees the Bengaluru project as a second earnings engine beyond the company's established Hyderabad portfolio. The new hotel will also expand Krishna GVK's presence into another major Indian business and hospitality market.
Monarch expects the combination of Taj Santacruz consolidation and Taj Yelahanka commissioning to change the company's earnings profile from FY27.
The expansion comes after a period in which the company had limited additions to its owned asset base. The brokerage sees the new properties as part of a fresh growth cycle.
Monarch estimates that Krishna GVK trades at 9.4 times FY27 estimated EV/EBITDA and 6.6 times FY28 estimated EV/EBITDA.
The brokerage said larger hospitality peers trade at around 14 to 15 times FY28 consensus EV/EBITDA. It believes Krishna GVK's earnings growth and expected returns support a smaller valuation discount than the stock currently reflects.
The valuation argument is also linked to the company's low leverage. Monarch said a discount of more than 10% to 15% against large cap peer multiples would be excessive and used an 8 times EV/EBITDA multiple on its FY29 estimates to arrive at the Rs 475 target.
The broader market has also seen sharp moves in individual stocks, including recent stock price movements, making company specific earnings and valuation factors important when assessing individual shares.
The brokerage's outlook depends on several operating and execution factors. The main factors to monitor are:
Monarch has also identified risks. These include a slower than expected ramp up at new properties, delays in project execution, weaker average room rates or occupancy growth and the company's dependence on Hyderabad.
The next major operating milestones are therefore the consolidation of Taj Santacruz and the planned opening of Taj Yelahanka. Their contribution to revenue and EBITDA will help determine whether the projected earnings growth develops as estimated.
Krishna GVK, formerly known as Taj GVK Hotels & Resorts, operates luxury hotels including Taj Krishna, Taj Deccan and Vivanta Hyderabad. Its portfolio also includes the Taj Santacruz property in Mumbai, where its stake has increased to 51%, while Taj Yelahanka is planned as a 256 key hotel in North Bengaluru.
The company's existing Hyderabad properties remain an important part of its business, while the Mumbai consolidation and Bengaluru project are expected to increase its owned hotel base and earnings contribution.
Monarch Network Capital Research has set a target price of Rs 475 for Krishna GVK shares. The brokerage started coverage with a BUY rating and said the target implies about 49% upside from the reference price of Rs 319.
Monarch expects Krishna GVK to benefit from higher room rates, Taj Santacruz consolidation and the planned Taj Yelahanka hotel in Bengaluru. The brokerage also points to strong existing hotel occupancy, low leverage and expected earnings growth.
Krishna GVK shares have gained around 126% over the past five years. However, the stock has fallen nearly 26% over the past year and remained about 27% below its 52 week high of Rs 438.85.
Taj Santacruz is expected to be fully consolidated from Q1FY27 after Krishna GVK increased its stake in the Mumbai property to 51%. Monarch expects the consolidation to increase reported revenue and EBITDA.
Taj Yelahanka, a 256 key luxury hotel in North Bengaluru, is expected to start operations in H2FY27. Monarch expects the property to become a second earnings engine for Krishna GVK.
Monarch has identified slower than expected ramp up of new properties, project execution delays, weaker room rate or occupancy growth and dependence on Hyderabad as the main risks to its outlook for Krishna GVK.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
Mphasis will maintain Social Security Scotland's benefits platform serving 2 million citizens. Shares closed at Rs 2,284.90 on October 6.
Kotak Mahindra Bank shares gained 9.8% in two months as loan growth improved. CEO clarity, asset quality, margins and the Rs 540 target are also in...
MobiKwik shares rose 20% to Rs 242.14 after 79.20 lakh shares changed hands in a Rs 189 crore block deal, with buyers and sellers undisclosed.
Reliance Industries shares rose 2.7% to Rs 1,218 as Jio Platforms IPO expectations grew, while Jefferies raised its portfolio weight to 7.5%.
Dabur India shares rose 3% to Rs 390 as the company expects double digit FMCG and revenue growth in Q2 FY27, with rural demand leading urban.