Loading market data...
Tue, 20 Oct 2026
04:56:29 pm
Tue, 20 Oct 2026
04:56:29 pm
Rudransh Sangwan
Published at: October 8, 2026, 6:37 PM
Synopsis
Bernstein sees US$30 million to US$35 million in FY27 Adempas sales for Zydus, with 10% to 12% market share and a 26.4% implied upside.
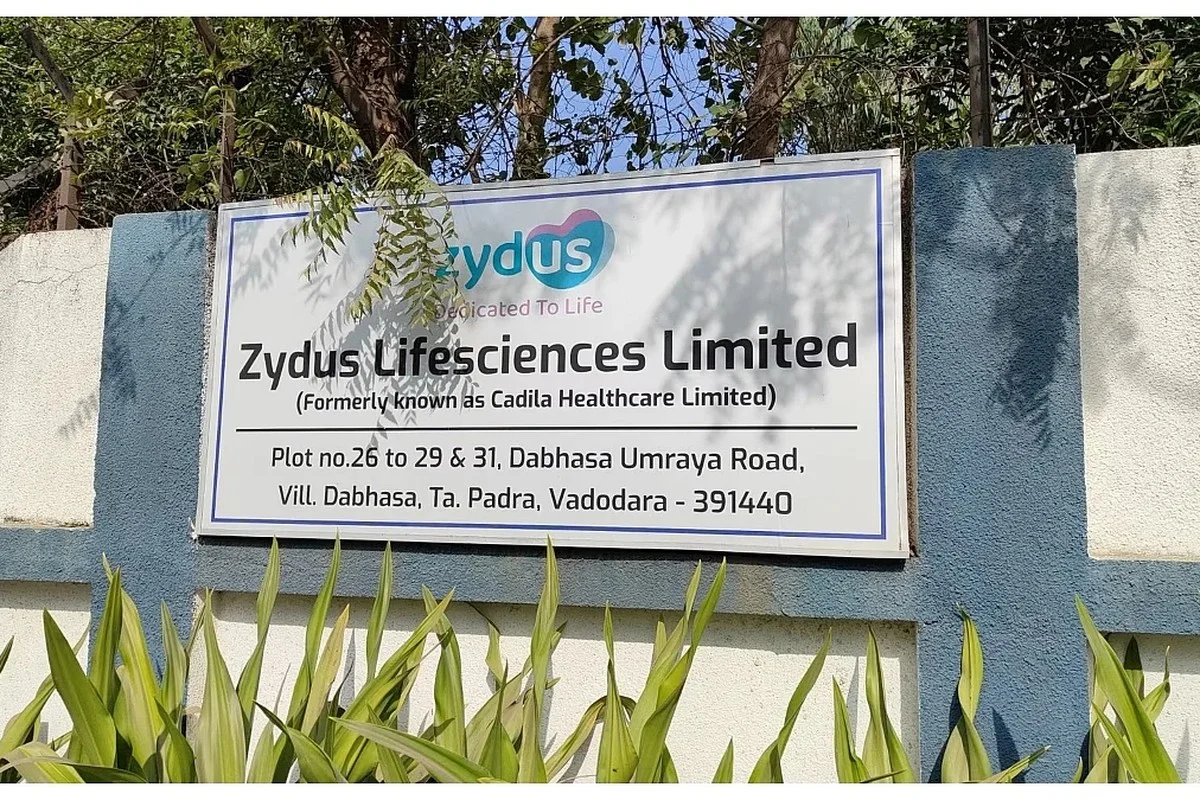
Bernstein has maintained an "Outperform" rating on Zydus Lifesciences with a target price of Rs 1,457 a share, after the company launched the first generic version of Bayer's Adempas in the United States. The target is about 26.4% above Zydus Lifesciences' October 7 closing price of Rs 1,153.
The brokerage estimates that the Adempas generic could add US$30 million to US$35 million in FY27 sales, assuming Zydus captures a 10% to 12% share during the October to March period. The estimate is based on Zydus having first to file status for the product.
The launch matters beyond the expected sales from Adempas. Bernstein sees it as further evidence that Zydus can use partnerships to bring differentiated Para IV generic products to the US market.
Loading chart...
The immediate financial contribution from the launch is relatively modest compared with the broader reasoning behind Bernstein's rating. The brokerage estimates that Adempas could generate Rs 1.9 billion to Rs 2.4 billion of revenue for Zydus in FY27.
At a contribution margin of 30% to 35%, Bernstein estimates that the launch could contribute about 0.7% to 1.0% of its FY27 earnings per share estimate. The brokerage's view therefore does not appear to rest only on the earnings contribution from this one product.
| Particulars | Details |
|---|---|
| Brokerage rating | Outperform, maintained |
| Target price | Rs 1,457 a share |
| October 7 closing price | Rs 1,153 |
| Implied upside | About 26.4% |
| Estimated FY27 sales | US$30 million to US$35 million |
| Estimated revenue | Rs 1.9 billion to Rs 2.4 billion |
| Estimated contribution margin | 30% to 35% |
| Estimated FY27 EPS contribution | 0.7% to 1.0% |
| Expected US market share | 10% to 12% |
The sales estimate assumes Zydus captures 10% to 12% of the US market during the October to March period. Bernstein's estimate is therefore tied to both the launch and the level of market share Zydus can achieve.
Adempas is the brand name for Bayer's product, and Zydus has launched the first generic version in the United States. The launch is linked to a Para IV opportunity.
A Para IV filing challenges a patent before the patent expires. If the challenge succeeds, the generic company can receive a period of exclusivity. That period can make such launches financially attractive, although developing and pursuing these products can require significant legal and technical work.
Bernstein's view is that the Adempas launch gives another example of Zydus using this model through a partnership. The brokerage said the launch "further reinforces Zydus' ability to commercialize differentiated Para IV opportunities through partnerships."
The partnership involves MSN and Zydus. MSN developed and manufactures the product, while Zydus handles commercialisation in the United States. This divides the work between development and manufacturing on one side, and US commercialisation on the other.
The structure gives each party a defined role in bringing the generic product to the US market. MSN carries the development and manufacturing work, while Zydus uses its US commercial capabilities to sell the product.
This model is important to Bernstein's broader assessment of Zydus. A company developing every product internally would depend more heavily on its own research and development capacity. A partnership model can allow a company to work on more product opportunities by combining outside development capabilities with its own commercial network.
The Adempas launch therefore provides a specific example of the operating model Bernstein is assessing. The brokerage's rating is linked to the potential for Zydus to pursue more differentiated Para IV opportunities through similar partnerships.
Zydus has also been in focus for its corporate actions, including its previously announced Zydus Lifesciences share buyback, which gives investors another recent company development to track alongside the US generic launch.
The estimated contribution from Adempas is relatively small in relation to Zydus' overall earnings. Bernstein expects the product to contribute 0.7% to 1.0% of its FY27 earnings per share estimate.
That means the immediate earnings impact from the launch is limited in the brokerage's estimates. The larger point in the rating is the potential for the partnership model to support additional differentiated generic launches.
Bernstein estimates US$30 million to US$35 million in FY27 sales from Adempas. Its revenue estimate of Rs 1.9 billion to Rs 2.4 billion is based on the expected US market share during the October to March period.
The margin assumption of 30% to 35% then translates that revenue estimate into the expected EPS contribution.
The next focus will be how the Adempas generic performs in the US market and whether Zydus can reach the 10% to 12% market share assumed by Bernstein. Actual sales could differ from the brokerage estimate depending on market share and commercial performance.
Investors will also watch whether Zydus continues to use partnerships for other Para IV opportunities. Bernstein's assessment places importance on the company's ability to commercialise differentiated products through this structure.
The main factors to monitor include:
Bernstein's Rs 1,457 target price remains a brokerage estimate and its "Outperform" rating is the brokerage's view. The target price and rating can change as new information becomes available.
Zydus Lifesciences is the company at the centre of the brokerage call. The development discussed here relates to its US generic drug business and its partnership with MSN for the Adempas generic.
The company is also the subject of an earlier Zydus Lifesciences buyback announcement, making its recent corporate activity relevant when tracking the stock.
The Adempas launch adds another development for the market to track, with Bernstein's estimates focused on the product's US sales, market share and the wider use of partnership based Para IV opportunities.
Bernstein's target price for Zydus Lifesciences is Rs 1,457 a share. The brokerage has maintained its "Outperform" rating after the launch of Zydus' first generic version of Bayer's Adempas in the United States.
The reference price for Zydus Lifesciences in Bernstein's call is Rs 1,153, based on the October 7 closing price. Bernstein's Rs 1,457 target represents an implied upside of about 26.4% from that level.
Zydus Lifesciences could generate US$30 million to US$35 million of FY27 sales from the Adempas generic, based on Bernstein's estimate. The estimate assumes a 10% to 12% market share during the October to March period.
A Para IV filing challenges a patent before the patent expires. For Zydus Lifesciences, Bernstein views the Adempas launch as an example of the company's ability to commercialise differentiated Para IV opportunities through partnerships.
MSN developed and manufactures the Adempas generic, while Zydus Lifesciences leads its commercialisation in the United States. The partnership divides development and manufacturing work from US commercialisation.
Bernstein estimates that Adempas could contribute 0.7% to 1.0% of its FY27 earnings per share estimate. The estimate is based on expected revenue of Rs 1.9 billion to Rs 2.4 billion and a 30% to 35% contribution margin.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
L&T has begun preliminary work on the New Tashkent International Airport project after receiving a limited notice to proceed.
DLF share price has 41% upside, according to HSBC’s target. Compare Jefferies, CLSA and other broker views on sales, cash flow and valuations.
Divi's Laboratories shares rose 1.01% to Rs 9,242.50 after a positive EU opinion on Eli Lilly's weight loss drug Foundayo. See the growth outlook.
Awfis revenue target exceeds Rs 1,800 crore for FY27, with flexible workspace demand supporting growth. Expansion and execution remain key to watch.
L&T has won a contract worth over Rs 15,000 crore. The client, project scope and execution timeline remain undisclosed, leaving its revenue impact...