Loading market data...
Tue, 20 Oct 2026
04:57:31 pm
Tue, 20 Oct 2026
04:57:31 pm
Rudransh Sangwan
Published at: October 16, 2026, 5:25 AM
Synopsis
Wipro Q2 FY27 results: Revenue rises 9.1% while profit falls 1.9%. See what Nomura, Goldman Sachs and Emkay said about Wipro shares.
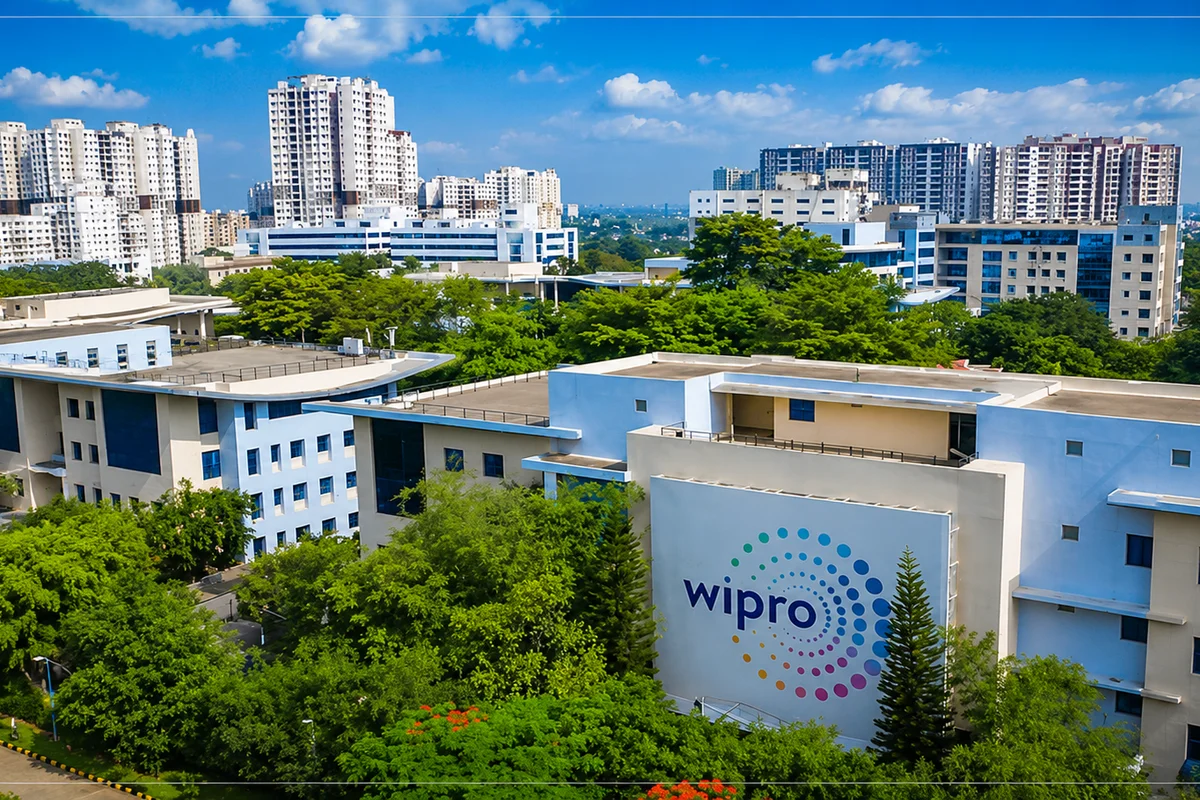
Wipro shares rose as much as 2.3% to ₹178 on the BSE on October 16 after the IT company reported 9.1% year on year revenue growth for the second quarter of FY27. However, net profit declined 1.9%, while its December quarter revenue outlook remained weak.
Brokerages have different views on Wipro's growth prospects, deal pipeline and profit margins.
| Financial metric | Q2 FY27 | Year on year change |
|---|---|---|
| Revenue | ₹24,752.7 crore | Up 9.1% |
| Net profit | ₹3,201 crore | Down 1.9% |
| IT services revenue | $2.61 billion | Down 0.1% quarter on quarter |
| IT services operating margin | 16.5% | Up 0.5 percentage points |
| Share price high | ₹178 | Up 2.3% |
Wipro's revenue increased 1.1% quarter on quarter. Its profit performance remained under pressure despite higher revenue.
Wipro expects revenue in the third quarter of FY27 to change by between a 1.5% decline and 0.5% growth sequentially in constant currency terms.
The company signed nine large deals during Q2. However, some expected deal signings were delayed by paperwork and pushed into the December quarter.
Management expects these deals to close and has pointed to a strong pipeline for Q3.
Brokerages differ in their assessment of Wipro's future growth, deal wins and valuation.
| Brokerage | View reported | Target price | Main reason |
|---|---|---|---|
| Nomura | Buy | ₹200 | Revenue slightly exceeded estimates, with delayed deals expected to close |
| Goldman Sachs | Sell | Not stated in the supplied report | Lower deal wins and limited revenue visibility |
| Emkay | Reduce | ₹170 | Weak order intake and subdued performance in some business segments |
These are the respective brokerages' views, not a consensus forecast.
Nomura raised its target price to ₹200 after Wipro's revenue slightly exceeded its estimates. It expects large deal closures to support future growth.
The brokerage forecasts dollar revenue growth of negative 0.5% in FY27 and 1.7% in FY28. It also expects EBIT margins of 16.4% to 17% across these years.
Goldman Sachs maintained its Sell rating despite the quarterly performance exceeding its expectations on revenue growth and margins.
It cited a 26% year on year decline in trailing 12 month deal wins, raising concerns about future revenue growth. The brokerage identified the appointment of an external CEO as a potential factor that could change investor perceptions.
Emkay retained its Reduce rating and ₹170 target price. It highlighted weak order intake and subdued performance in the healthcare, technology and communications segments.
However, Wipro's IT services operating margin improved by 0.5 percentage points to 16.5% during the quarter.
Wipro's performance will depend on whether delayed deals close, order intake improves and revenue growth strengthens. Its ability to maintain margins will also remain important.
The next quarter's results should provide more clarity on demand, deal conversion and progress towards the company's margin goals.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
L&T has begun preliminary work on the New Tashkent International Airport project after receiving a limited notice to proceed.
DLF share price has 41% upside, according to HSBC’s target. Compare Jefferies, CLSA and other broker views on sales, cash flow and valuations.
Divi's Laboratories shares rose 1.01% to Rs 9,242.50 after a positive EU opinion on Eli Lilly's weight loss drug Foundayo. See the growth outlook.
Awfis revenue target exceeds Rs 1,800 crore for FY27, with flexible workspace demand supporting growth. Expansion and execution remain key to watch.
L&T has won a contract worth over Rs 15,000 crore. The client, project scope and execution timeline remain undisclosed, leaving its revenue impact...