Loading market data...
Tue, 20 Oct 2026
04:58:06 pm
Tue, 20 Oct 2026
04:58:06 pm
Rudransh Sangwan
Published at: October 15, 2026, 5:30 PM
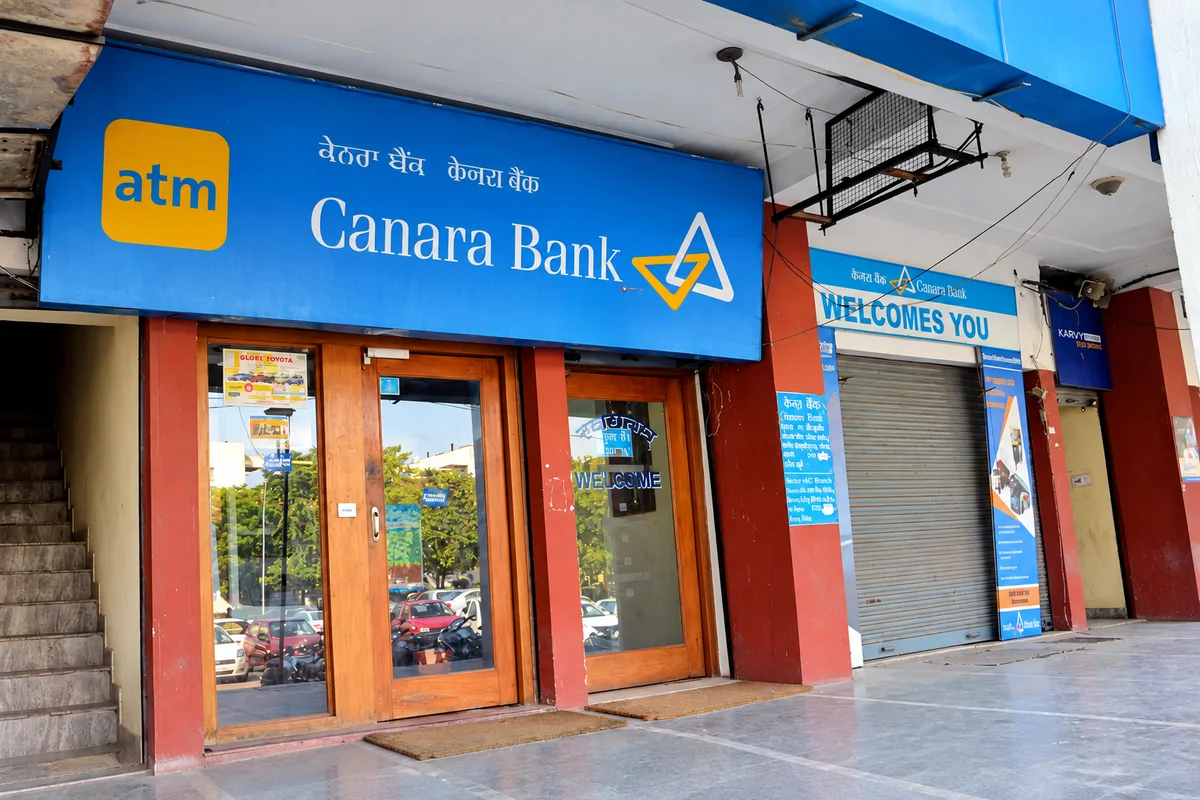
Prabhudas Lilladher has retained its Buy rating on Canara Bank and raised its target price to ₹160 from ₹150, according to a research report dated October 15, 2026. The brokerage cited better than expected quarterly performance and an improved outlook for core profit.
Canara Bank reported stronger core pre provision operating profit (PPoP), supported by higher net interest income, better net interest margins and fee income.
| Particular | Details |
|---|---|
| Brokerage | Prabhudas Lilladher |
| Rating | Buy |
| Target price | ₹160 |
| Previous target | ₹150 |
| Current share price | ₹117.20 |
| Report date | October 15, 2026 |
The reported share price of ₹117.20 implies a potential upside of about 36.5% to the brokerage's ₹160 target. This is a calculation based on the reported price and target, not a guaranteed return.
Canara Bank delivered a strong quarter, with core PPoP rising 13.3%. The brokerage attributed the performance to better net interest income, improved margins, fee income and operating expenses.
Loan growth was 6.5% quarter on quarter. Excluding FCNR(B) related loans, domestic credit growth was around 5%, mainly supported by corporate and agricultural lending.
Prabhudas Lilladher expects the bank's net interest margin to remain around current levels. It cited higher yields on corporate and agricultural loans, potential festive season retail credit demand, a loan to deposit ratio of around 80% and the repricing of external benchmark linked loans.
The brokerage raised its FY27 and FY28 net interest margin estimates by 7 basis points and 6 basis points, respectively. It also increased its core profit after tax estimates by an average of around 6%.
| Earnings metric | Brokerage update |
|---|---|
| Core PPoP growth | 13.3% |
| Loan growth | 6.5% quarter on quarter |
| Domestic credit growth excluding FCNR(B) loans | Around 5% quarter on quarter |
| FY27 NIM estimate | Raised by 7 basis points |
| FY28 NIM estimate | Raised by 6 basis points |
| Core PAT estimates | Raised by around 6% on average |
Prabhudas Lilladher has retained its Buy rating while raising the target price to ₹160, based on its updated estimates through September 2028. Future performance will depend on net interest margins, loan growth and the bank's ability to maintain earnings growth. The brokerage target is an estimate and does not guarantee future share price performance.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
No related topics available
L&T has begun preliminary work on the New Tashkent International Airport project after receiving a limited notice to proceed.
DLF share price has 41% upside, according to HSBC’s target. Compare Jefferies, CLSA and other broker views on sales, cash flow and valuations.
Divi's Laboratories shares rose 1.01% to Rs 9,242.50 after a positive EU opinion on Eli Lilly's weight loss drug Foundayo. See the growth outlook.
Awfis revenue target exceeds Rs 1,800 crore for FY27, with flexible workspace demand supporting growth. Expansion and execution remain key to watch.
L&T has won a contract worth over Rs 15,000 crore. The client, project scope and execution timeline remain undisclosed, leaving its revenue impact...