Loading market data...
Tue, 20 Oct 2026
04:57:07 pm
Tue, 20 Oct 2026
04:57:07 pm
Rudransh Sangwan
Published at: October 15, 2026, 7:55 AM
Synopsis
Nomura initiates Buy coverage on Paytm with a ₹2,250 target price, citing payments growth, merchant lending, AI efficiencies and potential UPI MDR revenue.
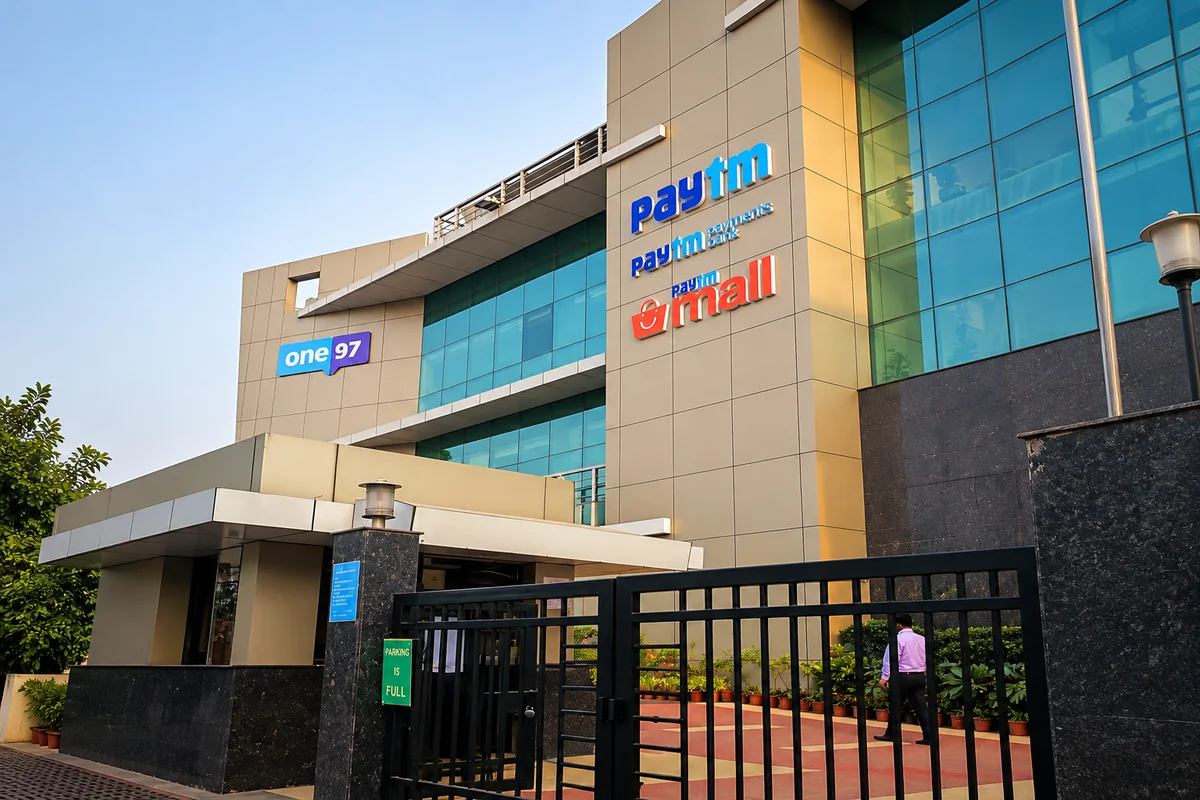
Paytm shares have gained 31.6% in 2026, while the Nifty 50 has fallen 12.4%. Nomura has initiated coverage with a Buy rating and a target price of ₹2,250, implying 31.4% upside from the previous close.
The brokerage expects payments, merchant lending and AI driven efficiencies to support earnings growth through FY29.
| Detail | Information |
|---|---|
| Brokerage | Nomura |
| Rating | Buy |
| Target price | ₹2,250 |
| Potential upside | 31.4% |
| EBITDA growth forecast | 96% CAGR from FY26 to FY29 |
| Valuation basis | 26 times estimated FY29 EV/EBITDA |
Paytm shares traded around ₹1,700 on October 15, 2026, giving the company a market capitalisation of approximately ₹1.09 lakh crore.
Nomura expects payments and merchant lending to remain Paytm's main growth drivers. A leaner cost structure, controlled marketing expenditure and AI driven efficiencies could improve profitability as the business expands.
The brokerage also sees potential from international expansion and merchant discount rates (MDR) on select UPI transactions. These opportunities could add revenue if the proposed framework is implemented.
Nomura forecasts EBITDA to grow at a compound annual growth rate of 96% between FY26 and FY29. This estimate reflects its expectation that revenue growth and operating efficiencies will improve earnings.
The National Payments Corporation of India (NPCI) has deferred the proposed UPI MDR framework until after Diwali. The delay initially pressured fintech stocks, including Paytm, Pine Labs and One Mobikwik Systems, before some losses were recovered.
Under the framework announced in September, a 0.4% MDR would apply to person to merchant UPI transactions above ₹2,000. Charges would be capped at ₹300 for transactions of ₹75,000 or more, with merchants bearing the cost. The final implementation date remains unannounced.
NPCI has indicated that around 96% of UPI transaction volumes and 75% of transaction value would remain outside the proposed charging framework.
Nomura has identified weaker lending asset quality and rising competition as risks. The brokerage's target price also depends on its earnings forecasts and valuation assumptions, so the projected upside is not guaranteed.
Investors should monitor Paytm's earnings, loan quality, competition and the final UPI MDR rules before making investment decisions.
Nomura has a Buy rating and a target price of ₹2,250, implying 31.4% upside from the previous close cited in the report.
The brokerage expects payments, merchant lending, AI driven efficiencies and potential UPI MDR revenue to support growth.
Nomura expects EBITDA to grow at a 96% CAGR between FY26 and FY29.
The main risks identified are weaker lending asset quality and intensifying competition. The final UPI MDR framework also remains uncertain.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
L&T has begun preliminary work on the New Tashkent International Airport project after receiving a limited notice to proceed.
DLF share price has 41% upside, according to HSBC’s target. Compare Jefferies, CLSA and other broker views on sales, cash flow and valuations.
Divi's Laboratories shares rose 1.01% to Rs 9,242.50 after a positive EU opinion on Eli Lilly's weight loss drug Foundayo. See the growth outlook.
Awfis revenue target exceeds Rs 1,800 crore for FY27, with flexible workspace demand supporting growth. Expansion and execution remain key to watch.
L&T has won a contract worth over Rs 15,000 crore. The client, project scope and execution timeline remain undisclosed, leaving its revenue impact...