Loading market data...
Tue, 20 Oct 2026
03:28:29 pm
Tue, 20 Oct 2026
03:28:29 pm
Rudransh Sangwan
Published at: October 9, 2026, 6:57 AM
Synopsis
KEC International's new contracts span transmission lines, wind power and cables, while Kotak expects 6% EBITDA margins and slower earnings recovery.
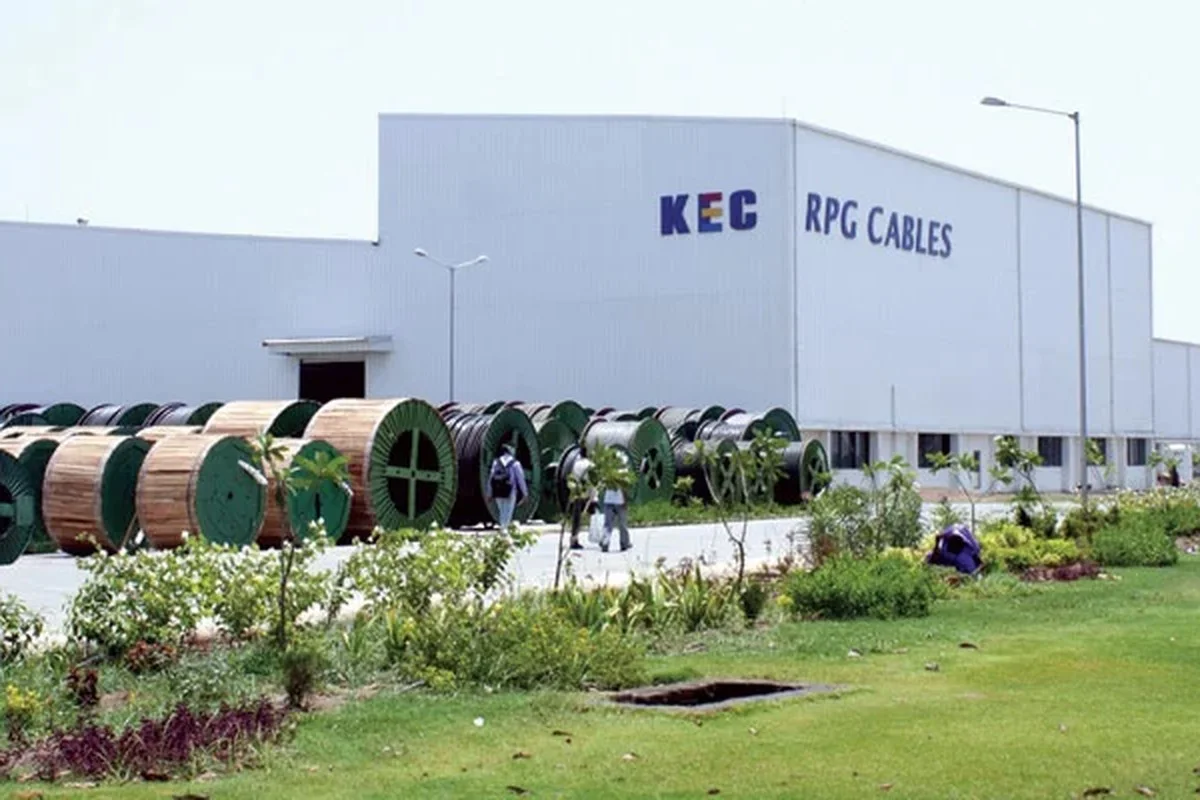
KEC International shares gained after the infrastructure engineering company secured new orders worth Rs 1,030 crore across its transmission and distribution, renewable energy, and cables businesses. The company disclosed the order wins in a regulatory filing dated October 8.
The new contracts include transmission line projects in Bhutan and Saudi Arabia, a wind power project in southern India, and orders for cables, conductors, towers, hardware and poles. The order wins come as the company works through execution delays and margin pressure across some of its business segments.
Kotak Institutional Equities upgraded its rating on KEC International to "Add", while reducing its target price to Rs 400 from Rs 470. The brokerage also cut its earnings per share estimates for FY2027 to FY2029 by 6% to 26%, reflecting expectations of a slower recovery in profitability.
Loading chart...
KEC International secured contracts across several business divisions, with transmission and distribution accounting for multiple orders. The company said its T&D business won a contract for a 400 kV transmission line in Bhutan and an additional order for a 380 kV transmission line in Saudi Arabia. It also received orders to supply towers, hardware and poles in the Americas.
The renewable energy division secured an order for a wind power project with a capacity of more than 300 MW from a private developer in southern India. Separately, the Cables and Conductors business received orders in India and overseas markets. The latest wins add to the company's project pipeline across domestic and international markets.
| Business segment | Order details |
|---|---|
| Transmission and distribution | 400 kV transmission line in Bhutan |
| Transmission and distribution | Additional 380 kV transmission line in Saudi Arabia |
| T&D supply business | Towers, hardware and poles in the Americas |
| Renewables | Wind project exceeding 300 MW in southern India |
| Cables and conductors | Orders in India and international markets |
| Total order value | Rs 1,030 crore |
The new contracts cover different parts of KEC International's infrastructure business. Transmission lines support electricity transmission networks, while the wind project adds to its renewable energy work. Orders for cables, conductors and related equipment provide business across the supply chain.
KEC International shares were trading at Rs 353.45 on the BSE at 11:10 am on Friday, up 1.03% at that time. The stock had risen by more than 4% earlier in the session following the order announcement.
Kotak Institutional Equities upgraded its rating to "Add" but lowered its target price to Rs 400 from Rs 470. The revised target reflects a more cautious earnings outlook, even as the brokerage sees scope for KEC International to benefit from spending on domestic transmission infrastructure.
| Particulars | Details |
|---|---|
| BSE share price at 11:10 am | Rs 353.45 |
| Price movement at that time | Up 1.03% |
| Intraday rise reported | More than 4% |
| Revised Kotak target price | Rs 400 |
| Previous target price | Rs 470 |
| Rating | Upgraded to Add |
| FY2027 to FY2029 EPS estimate cuts | 6% to 26% |
The target price reduction indicates that the rating upgrade does not amount to a more optimistic earnings forecast. Kotak's assessment combines the company's position in transmission infrastructure with concerns about margins, project execution and overseas operations.
KEC International's share price had corrected by more than 60% over the preceding year, according to the supplied market data. Kotak attributed the weakness to several operating challenges, including margin pressure in the civil and railway businesses, slower execution in the water segment because of delayed payments, a seven month debarment from participating in PCIL tenders, and disruptions to project execution in the Middle East amid geopolitical tensions.
These issues have affected the company's ability to execute projects at the pace and profitability previously expected. Delays in closing older projects can also affect the timing of revenue recognition and the recovery of margins.
Kotak expects margin pressure to continue over the next four quarters. The brokerage models EBITDA margins of 6% through the second half of FY2028 as KEC International completes legacy projects. EBITDA refers to earnings before interest, tax, depreciation and amortisation. The margin measures how much of a company's revenue remains as operating earnings before those costs.
The estimate changes reflect this more gradual recovery. Kotak cut its FY2027 to FY2029 earnings per share estimates by 6% to 26%, with the size of the reduction varying by financial year.
Kotak expects KEC International to record revenue growth of 10% in FY2027, below management's guidance of 12% to 15%. The brokerage cited continued uncertainty in the Middle East and delays in closing legacy projects as reasons for its more conservative estimate.
The brokerage also expects an EBITDA margin of 6% in FY2027. Its estimates for FY2028 and FY2029 were reduced by 11% and 6%, respectively, to account for a slower recovery in margins.
| Financial year | Revised estimate or change |
|---|---|
| FY2027 revenue growth | 10% |
| Management's FY2027 revenue growth guidance | 12% to 15% |
| FY2027 EBITDA margin assumption | 6% |
| FY2028 estimate reduction | 11% |
| FY2029 estimate reduction | 6% |
| FY2027 to FY2029 EPS estimate reductions | 6% to 26% |
The difference between management's revenue guidance and Kotak's forecast reflects uncertainty over project execution. Revenue growth alone may not be enough to improve profitability if costs remain high or projects take longer to complete.
The next few quarters will therefore be important for assessing whether new orders translate into timely execution and better operating margins.
Kotak believes KEC International is positioned to benefit from the expansion of India's transmission infrastructure, citing its execution record and established T&D business. The brokerage also expects the company's order pipeline across India and overseas markets, along with a higher contribution from cables, to support a gradual recovery in execution and margins.
The latest order announcement adds to KEC International's activity across transmission, renewable energy and cables. However, the value of new orders does not by itself establish when the contracts will be executed or how much profit they will generate. The impact will depend on project timelines, costs and the company's ability to manage execution challenges.
KEC International has previously announced other order wins across its businesses, including a Rs 1,754 crore order package across transmission and cables. It has also reported orders across T&D, renewables and civil infrastructure, showing activity across several operating divisions.
KEC International's new orders and Kotak's revised estimates point to two separate factors for the coming quarters: demand for infrastructure projects and the company's ability to execute them profitably.
Investors will be watching:
The company's ability to close legacy projects and manage costs will be important in determining whether margins recover as expected. Further updates on execution and financial performance will help clarify how quickly the business can move towards the recovery projected by the brokerage.
KEC International shares rose after the company announced new orders worth Rs 1,030 crore across its businesses. The contracts include transmission lines, a wind project exceeding 300 MW, and orders for cables, conductors, towers, hardware and poles.
Kotak Institutional Equities set a target price of Rs 400 for KEC International, down from Rs 470 earlier. The brokerage upgraded its rating to "Add" while cutting its earnings estimates for FY2027 to FY2029.
KEC International received orders worth Rs 1,030 crore, including a 400 kV transmission line project in Bhutan, an additional 380 kV line in Saudi Arabia, and a wind project exceeding 300 MW in southern India. Its cables and conductors business also secured orders in domestic and international markets.
Kotak reduced its FY2027 to FY2029 earnings per share estimates by 6% to 26% because of margin pressure, delays in completing legacy projects and uncertainty in the Middle East. It expects an EBITDA margin of 6% in FY2027 and a slower recovery in subsequent years.
Kotak expects KEC International's revenue to grow by 10% in FY2027, below management's guidance of 12% to 15%. The brokerage cited uncertainty in the Middle East and delays in closing older projects.
Investors can monitor KEC International's order execution, revenue growth, operating margins and project payment cycles. The brokerage expects margin pressure to persist over the next four quarters, with a gradual recovery dependent on execution and contributions from transmission and cables.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
L&T has begun preliminary work on the New Tashkent International Airport project after receiving a limited notice to proceed.
DLF share price has 41% upside, according to HSBC’s target. Compare Jefferies, CLSA and other broker views on sales, cash flow and valuations.
Divi's Laboratories shares rose 1.01% to Rs 9,242.50 after a positive EU opinion on Eli Lilly's weight loss drug Foundayo. See the growth outlook.
Awfis revenue target exceeds Rs 1,800 crore for FY27, with flexible workspace demand supporting growth. Expansion and execution remain key to watch.
L&T has won a contract worth over Rs 15,000 crore. The client, project scope and execution timeline remain undisclosed, leaving its revenue impact...