Loading market data...
Tue, 20 Oct 2026
02:21:18 pm
Tue, 20 Oct 2026
02:21:18 pm
Rudransh Sangwan
Published at: October 19, 2026, 6:22 AM
Synopsis
DLF share price has 41% upside, according to HSBC’s target. Compare Jefferies, CLSA and other broker views on sales, cash flow and valuations.
The short version
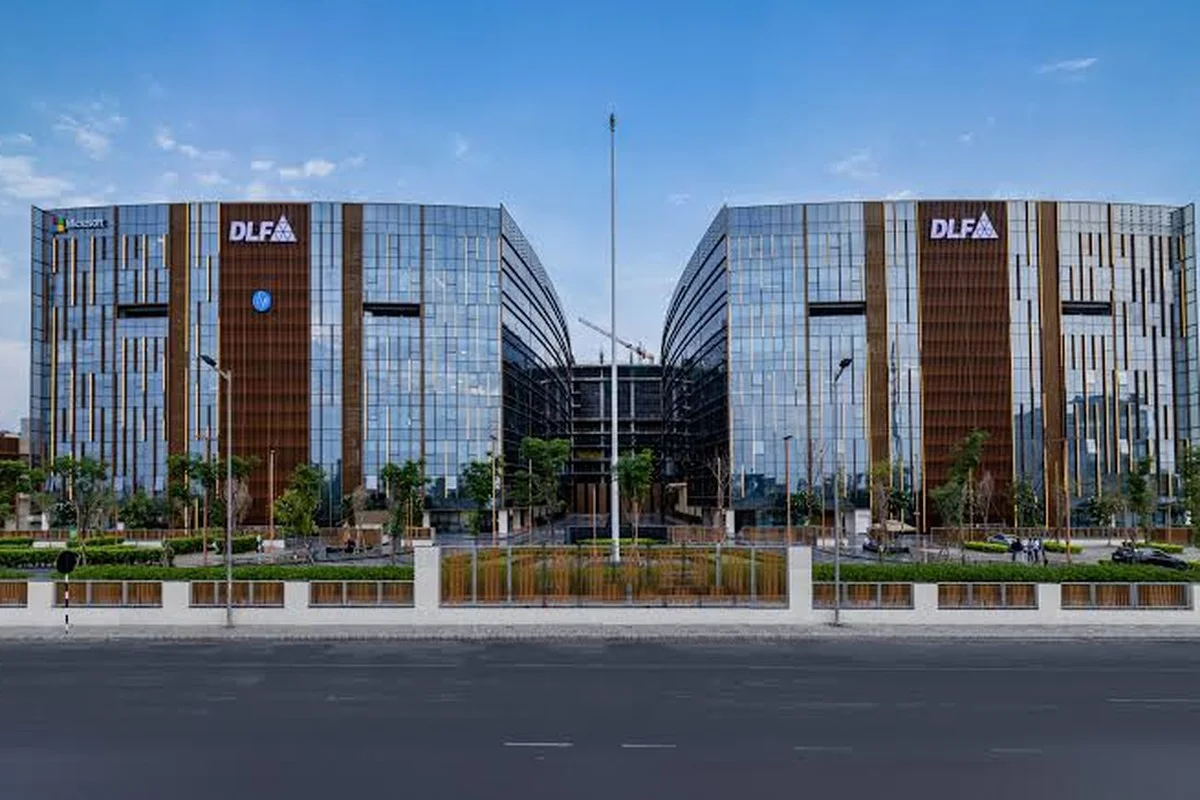
DLF shares traded at Rs 676.25 on Monday, October 19, up 0.2% after the company's September quarter results. HSBC raised its target price to Rs 950 from Rs 920 and retained its Buy rating. Other global brokerages also maintained positive views, with their price targets reflecting different expectations for sales, cash generation and revenue recognition.
Loading chart...
The price targets range from Rs 740 at Nomura to Rs 950 at HSBC. Jefferies has set a target of Rs 830, CLSA has a target of Rs 810, and JPMorgan has set a target of Rs 800. These estimates use Friday's closing price of Rs 675 as the reference point, so the implied upside figures are analyst projections rather than guaranteed returns.
DLF's September quarter presales reached Rs 3,800 crore, supported by demand for its residential projects. Brokerages also pointed to cash collections and the company's leasing business. However, expectations for revenue and earnings differ, with some analysts anticipating stronger revenue recognition in later quarters.
HSBC has the highest target among the five brokerages covered, while Nomura has the lowest. The spread reflects differences in their estimates for DLF's future performance and the pace at which property sales translate into reported revenue.
| Brokerage | Rating | Target price | Implied upside |
|---|---|---|---|
| HSBC | Buy | Rs 950 | 41% |
| Jefferies | Buy | Rs 830 | 23% |
| CLSA | Outperform | Rs 810 | 20% |
| JPMorgan | Overweight | Rs 800 | 19% |
| Nomura | Buy | Rs 740 | 10% |
HSBC's revised target increased by Rs 30 from its earlier estimate of Rs 920. Jefferies expects new launches and luxury home demand to support sales, while CLSA and JPMorgan have highlighted the latest presales recovery. Nomura also sees the sales performance as supportive, although it flagged weaker than expected revenue and EBITDA.
The wider analyst consensus is positive. Of the 24 analysts covering DLF, 22 have a Buy rating, one has a Hold rating and one has a Sell rating. The consensus price targets imply more than 22% upside from Friday's closing price, according to the figures in the source material.
DLF recorded presales of Rs 3,800 crore in the September quarter, a recovery from the preceding quarter. JPMorgan calculated that presales rose 478% sequentially but fell 12% year on year. The total exceeded Nomura's estimate of Rs 2,500 crore, giving the brokerage greater confidence that DLF remains on track to achieve its full year sales guidance.
The Aureva senior living project contributed around Rs 1,900 crore after selling out. DLF's Dahlias and Camellias projects accounted for the remaining Rs 1,900 crore cited in JPMorgan's assessment. At Dahlias, property realisations crossed Rs 1 lakh per square foot, with prices rising 10% sequentially.
DLF is targeting Rs 20,000 crore in presales for FY27. Jefferies expects a revival in new launches and sustained demand for luxury homes to support that goal. CLSA also expects launches planned for the second half of FY27 to help DLF achieve its annual target.
Presales refer to the value of homes sold or booked during a period. They are different from recognised revenue, which is recorded under the applicable accounting rules as projects progress. This distinction matters for DLF because strong bookings do not necessarily translate into an immediate increase in reported revenue or earnings.
JPMorgan highlighted improvements in DLF's collections and operating cash flow. Collections rose 4% year on year to Rs 2,780 crore, while net operating cash flow increased 37% to Rs 1,860 crore. Net free cash flow before dividends rose 27% to Rs 1,440 crore.
| Financial measure | September quarter figure | Change |
|---|---|---|
| Presales | Rs 3,800 crore | Up 478% sequentially |
| Collections | Rs 2,780 crore | Up 4% year on year |
| Net operating cash flow | Rs 1,860 crore | Up 37% year on year |
| Net free cash flow before dividends | Rs 1,440 crore | Up 27% year on year |
| Development business net cash | Rs 15,100 crore | Broadly stable after dividends |
These figures suggest that DLF collected more cash from customers while generating higher operating cash flow during the quarter. JPMorgan said the development business's net cash position remained broadly stable at Rs 15,100 crore after dividend payments.
Jefferies separately highlighted a net cash position of Rs 61 per share for DLF's development business. The figure provides another measure of the cash available within that business. Cash generation can support construction spending, future project development and shareholder distributions, although the eventual allocation of funds depends on the company's plans.
CLSA also expects operating cash flow to benefit from higher collections and lower operating expenses. Its assessment points to the importance of tracking cash actually received from buyers alongside the value of new bookings.
Jefferies retained its Buy rating with a target price of Rs 830. Its assessment rests on the expected revival in new launches and continuing demand for luxury housing. The brokerage expects these factors to support the Rs 20,000 crore FY27 presales target.
DLF's leasing business is another part of the assessment. Jefferies noted that occupancy remained above 95%, indicating high utilisation of its leased properties. However, it expects DLF's financial performance in FY27 to remain uneven, even after a better than expected contribution from other income in the September quarter.
CLSA maintained its Outperform rating and Rs 810 target price. Beyond the latest sales figures, the brokerage expects DLF to complete 11 million to 12 million square feet of annuity assets by FY30. Annuity assets generally generate recurring income, including rental income from commercial properties.
CLSA expects FY28 could be an inflection point for revenue recognition. That forecast suggests reported revenue may take time to catch up with sales bookings, depending on project execution and the timing of handovers.
Readers following other brokerage views can also review Jefferies ratings on selected stocks and its stock targets across several sectors. These provide context on how brokerage ratings and target prices are presented across different companies.
JPMorgan maintained an Overweight rating with a target of Rs 800. Alongside the rise in presales and cash flow, its assessment included the performance of DLF's premium residential projects. The Dahlias realisation above Rs 1 lakh per square foot and the sequential price increase of 10% indicate the pricing levels achieved in that project.
Nomura retained its Buy rating but set a more conservative target of Rs 740. It noted that presales beat its estimate, while revenue and earnings before interest, taxes, depreciation and amortisation, or EBITDA, fell below consensus estimates. This gap shows why property bookings alone may not capture the full picture of quarterly financial performance.
Nomura expects stronger revenue recognition from the September quarter of FY28. It also estimates annual free cash flow of Rs 7,000 crore to Rs 8,000 crore, which it sees as supporting shareholder returns and new business development. The brokerage expects annuity income to grow at a compound annual growth rate of 12% to 13% as additional assets become operational.
Execution in luxury and super luxury housing remains another factor in Nomura's assessment. Project delivery schedules, customer collections and the timing of revenue recognition will influence how quickly the sales pipeline feeds into reported financial results.
DLF shares were up 0.2% at Rs 676.25 on Monday, October 19. The stock had gained 2% over the previous month but was down 2% so far in 2026, based on the figures supplied. The limited movement suggests that the latest results had not produced a large price change at the time covered.
The brokerages' targets indicate room for a higher valuation in their forecasts, but those targets depend on future performance. Presales growth, the launch schedule and cash generation support the positive assessments. Weaker revenue and EBITDA relative to consensus estimates remain counterpoints.
The difference between a target price and the current market price is an estimate of potential price movement over the brokerage's forecast period. Actual returns can differ because financial results, project timelines, property demand and broader market conditions may change.
The next phase of DLF's performance will depend on whether the company converts its residential demand into sustained sales and recognised revenue. The following figures are particularly relevant:
DLF's reported occupancy above 95% also gives investors a measure of leasing performance to track alongside residential sales. Rental income from new commercial assets could support recurring cash generation as those properties become operational.
DLF is an Indian real estate developer with residential development and leasing businesses. Its residential portfolio includes luxury and super luxury projects such as Aureva, Dahlias and Camellias. Its leasing operations generate recurring income from commercial assets.
The combination of residential bookings and rental income means that DLF's financial performance depends on different business cycles. Investors will be watching upcoming launches and project execution alongside the pace of revenue recognition in FY28.
HSBC has a target price of Rs 950 for DLF shares and retains its Buy rating. The target was raised from Rs 920 and implies about 41% upside from the reference closing price of Rs 675.
Jefferies has a target of Rs 830, CLSA has set Rs 810 and JPMorgan has a target of Rs 800. Their respective implied upside estimates are 23%, 20% and 19% from Rs 675.
DLF recorded presales of Rs 3,800 crore in the September quarter. JPMorgan calculated a 478% sequential increase and a 12% year on year fall. The Aureva project contributed around Rs 1,900 crore after selling out.
DLF's presales target for FY27 is Rs 20,000 crore. Jefferies and CLSA expect new launches in the second half of the financial year to support progress towards this goal.
Nomura noted that DLF's September quarter presales exceeded its estimate, but revenue and EBITDA were below consensus estimates. The brokerage expects stronger revenue recognition from the September quarter of FY28.
Of the 24 analysts covering DLF in the supplied figures, 22 have a Buy rating, one has a Hold rating and one has a Sell rating. Their consensus price targets imply more than 22% upside from the Rs 675 reference closing price.
Financial journalist specializing in market analysis, stock research, and investment trends. Dedicated to providing accurate, timely insights for informed decision-making.
Credentials: Experienced financial journalist with expertise in equity markets and economic analysis
The information provided in this article is for educational and informational purposes only and should not be construed as financial, investment, or legal advice. welomoney does not provide personalized investment recommendations.
For detailed terms and conditions, please read our Disclaimer and Terms of Service.
L&T has begun preliminary work on the New Tashkent International Airport project after receiving a limited notice to proceed.
Divi's Laboratories shares rose 1.01% to Rs 9,242.50 after a positive EU opinion on Eli Lilly's weight loss drug Foundayo. See the growth outlook.
Awfis revenue target exceeds Rs 1,800 crore for FY27, with flexible workspace demand supporting growth. Expansion and execution remain key to watch.
L&T has won a contract worth over Rs 15,000 crore. The client, project scope and execution timeline remain undisclosed, leaving its revenue impact...
Suzlon share price fell nearly 3% to Rs 40.83 amid a decline of over 20% in six months. Analysts identify Rs 38 support and Rs 46 as a near term...